
The digital euro is coming — and Europe should be afraid of what comes with it
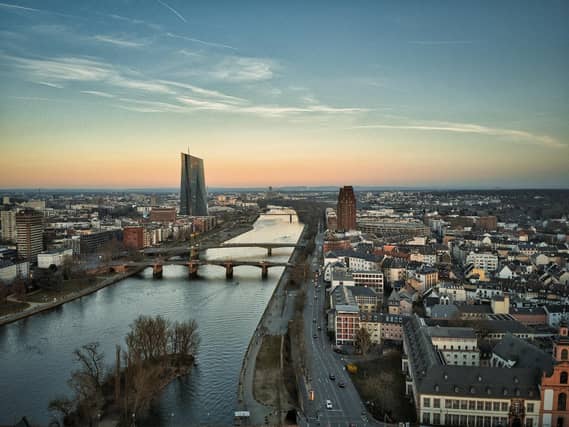

The European Central Bank plans to have a digital euro ready by 2029. Officials describe it as modern, free and safe. The reality looks far less reassuring.
The European Central Bank plans to have a digital euro ready by 2029. Officials describe it as modern, free and safe. The reality looks far less reassuring.
The ECB says preparations could finish by 2029, with pilot tests starting in 2027 if EU lawmakers approve new rules by 2026. This would create a central bank digital currency for the eurozone, known as a CBDC. Once launched, it would give the state a direct role in how money moves through the economy.
In a joint article titled A digital euro for the digital age, ECB Executive Board member Piero Cipollone and European Commission Vice President Valdis Dombrovskis say the digital euro would exist alongside cash. They promise that banknotes and coins will remain available and accepted everywhere.
Dombrovskis wrote on the ECB blog: “The ECB plans to prepare for the potential issuance of the digital euro by 2029, assuming the European co-legislators adopt the necessary regulation by 2026. Preparatory steps, including pilot exercises and initial transactions, could begin as early as mid-2027.”
The Commission has already introduced the Single Currency Package. One law is meant to protect access to cash. The second law creates the legal framework for the digital euro itself. The ECB says the digital euro would be free, easy to use, widely available and private in a way that resembles cash. It would work online and offline, even without an internet connection.
These assurances sound comforting. History gives no reason to trust them.
At present, the only public money ordinary people can hold directly is physical cash. Every digital payment already depends on private banks and payment firms. A digital euro would place the central bank inside everyday transactions for the first time.
Cipollone and Dombrovskis stress the emotional and social role of cash. They wrote: “Cash brings us together. We know we can rely on cash. It is accepted throughout the euro area. It is easy to use and inclusive. It protects privacy. And it is our money, issued by a public institution, the European Central Bank.”
They also argue that more people now pay digitally and need a digital form of cash to match modern habits. That shift already exists through private payment systems. The digital euro adds state control to a system that already works.
In another ECB blog, Why Europe needs a digital euro, Dombrovskis and ECB board member Fabio Panetta argue that central banks worldwide are moving in the same direction. They say a digital euro would give everyone a free payment option across the euro area while cash remains in place.
The promise rests on permanent restraint by future governments and central banks. Power rarely works that way.
On 30 October, the ECB plans to publish The Digital Euro Scheme Rulebook. This document will standardise digital euro payments across all eurozone countries. The ECB says users will get the same experience everywhere, regardless of provider.
Standardisation also makes control easier. A single rulebook creates a single system. A single system can be changed centrally.
Banks already warn of major damage. A study by European banking associations estimates that each bank would face average costs of €110 million to implement the digital euro. The total bill across the euro area would reach €18 billion. These costs will not vanish. Customers will pay them.
Opposition has also emerged in the European Parliament. Lawmakers raise concerns about privacy, financial stability and innovation. Spanish MEP Fernando Navarrete Rojas, who is drafting Parliament’s digital euro report, questions the need for the project at all. In his paper Do we really need the digital euro: A solution to what problem exactly?, he challenges the claimed benefits and warns about risks to privacy and stability. He argues that Europe should invest in private European payment systems instead.
This scepticism reflects a wider truth. Governments repeatedly promise safeguards when new financial powers are introduced. Those safeguards weaken over time. Central bank digital currencies create a mechanism that allows money to be monitored, restricted or redirected. The temptation to use that power grows during crises.
Businesses face serious risks. A CBDC can become a tool in political disputes between states, disrupting payments and trade. At home, companies could face pressure to follow political rules tied directly to access to money. Managers could see personal views turn into commercial liabilities.
The digital euro is presented as progress. It concentrates power in the hands of the state. Once built, it will not remain unused.
Lionel Eddy is a journalist specialising in digital identity, biometrics and state surveillance, and the author of The Digital Agenda.
By Lionel Eddy for Belters News